Before the RESP, the hockey fees and the down payment help: do this first
Parents are told to put their children first.
It’s generally excellent life advice.
Financially, it can be terrible advice.
Should you contribute $5,000 to your child’s RESP while carrying $12,000 on a credit card? Keep paying for competitive hockey without an emergency fund? Help your adult child with a down payment when you’re badly behind on retirement?
These aren’t easy choices, particularly when raising kids gets more expensive.
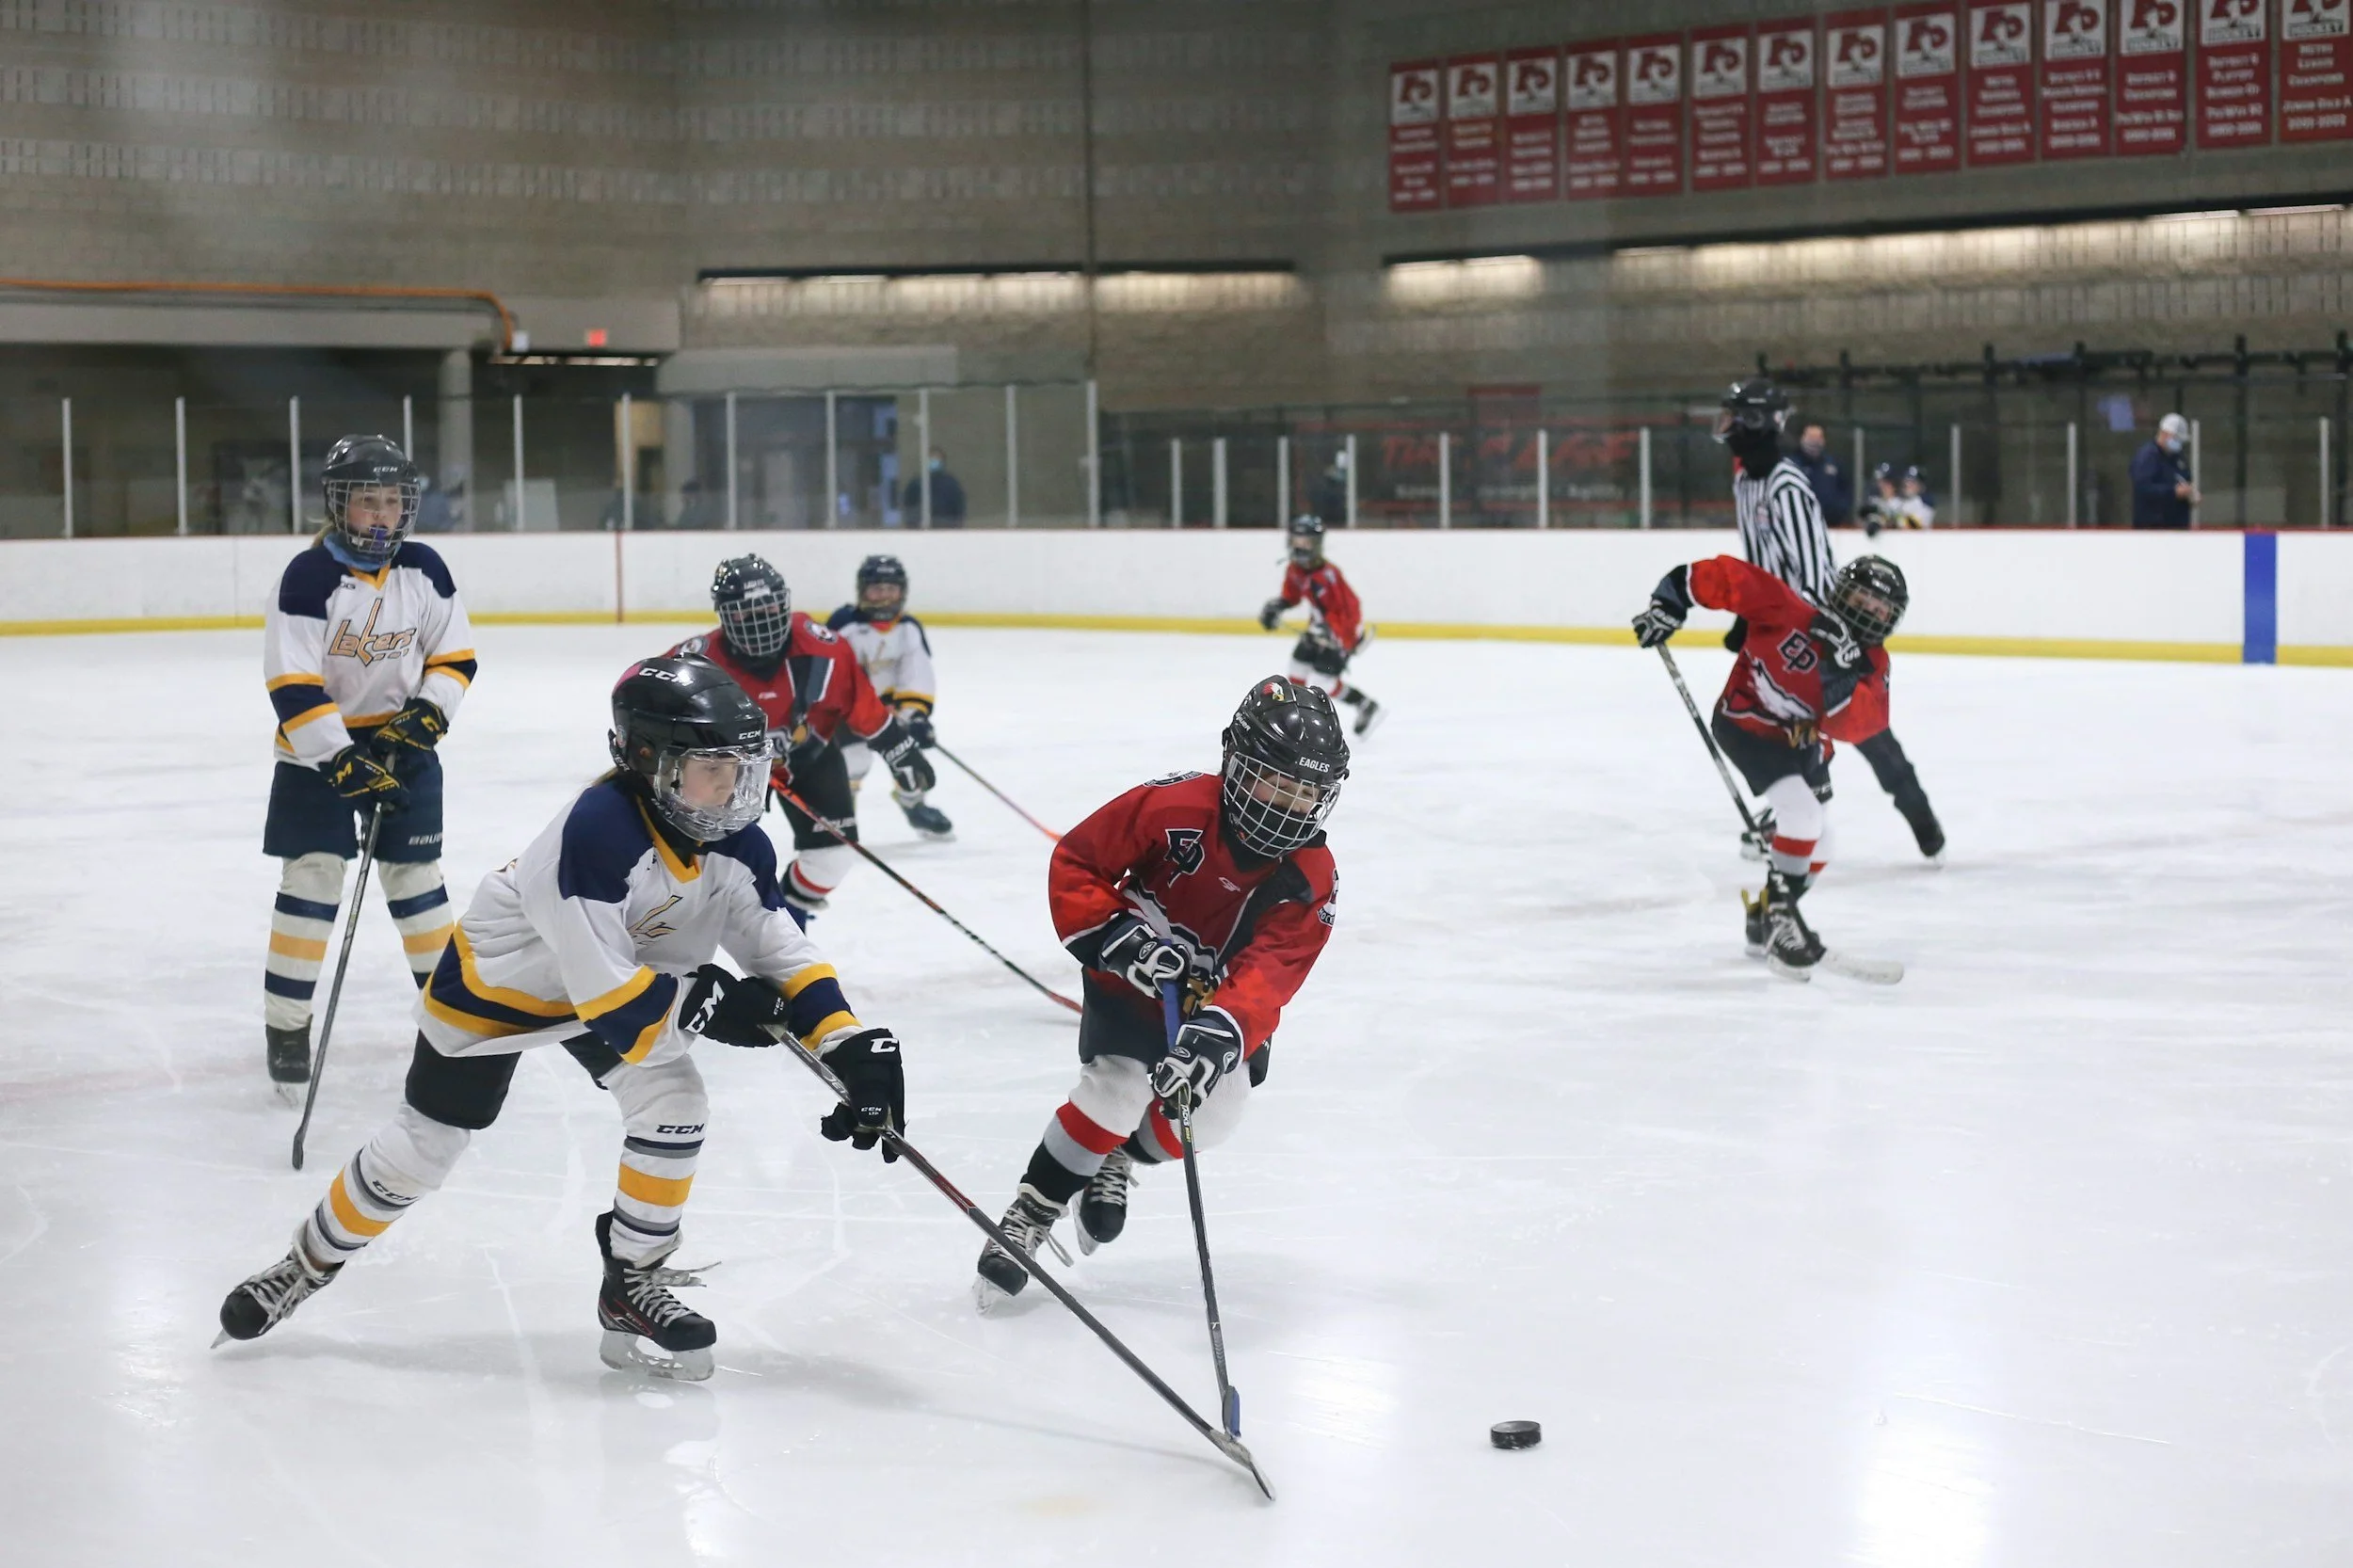
Canadian families spend an average of $2,140 annually per child on organized sports, according to Canadian Tire Jumpstart. Competitive hockey, dance, gymnastics and other activities can quickly eclipse those averages once equipment, travel, hotels and tournament fees enter the picture.
Meanwhile, groceries, housing and practically everything else cost more than they used to.
Protect the family first
Before maximizing an RESP or signing up for another activity, protect the household itself. Keep essential bills paid, maintain appropriate insurance, and don’t jeopardize housing or groceries to fund things that can wait.
This isn’t selfish. Financial stability is something you’re providing your children too. An emergency fund doesn’t just protect your bank account — it protects your mental health, creating breathing room when life inevitably throws something expensive your way.
Start by separating your family’s expenses into two categories: what protects your household and what enhances your lifestyle. Fund protection first.
Stabilize before you optimize
If a $2,500 car repair would immediately land on a credit card with no flexibility to pay it off, build some emergency savings before aggressively funding optional goals. Start with $25 per week into a separate savings account, or more if you can afford it.
Think ahead for larger one-time costs
Not every big expense is an emergency. Hockey, summer camp and other activities can add up quickly, but they’re predictable. Nearly six in 10 parents say they’ve cut spending elsewhere, borrowed money or taken on extra work to help cover the cost of their kids’ sports.
A separate savings account helps. If hockey will cost $3,600 this year, automatically saving $300 a month means the money is ready when the bills roll in — and not landing on your credit card. The same strategy works for property taxes, insurance premiums, and other predictable lump-sum costs.
Eliminate the expensive debt
This is where parents can struggle emotionally. Putting $200 into an RESP feels like doing something meaningful for your child. Putting the same $200 against a credit card doesn’t produce the same warm feeling. But persistent high-interest debt can destabilize the entire household.
If you’re carrying debt at 20-plus per cent, aggressively paying it down may do more for your child’s long-term financial security than maximizing their RESP this year. Rank your debts by interest rate and tackle the most expensive ones first, while maintaining required minimum payments elsewhere.
Build your future, too
Once you’ve created stability and high-interest debt is under control, build long-term wealth. That may mean prioritizing your own retirement alongside — or even ahead of — some goals for your children. Your child has options for funding post-secondary education, including employment income, scholarships, grants and student loans.
There is no student loan for your retirement.
Before increasing RESP contributions or saving toward your child’s down payment, check whether you’re on track for your own retirement. Are you regularly contributing to your TFSA or RRSP? Are you taking full advantage of an employer retirement savings program and any matching contributions?
Then give generously
Once the family’s foundation is secure, spend intentionally on the things you value: sports, camps, travel, RESPs — and eventually, perhaps, help with a first car, wedding or home.
The goal isn’t to stop spending on your children. It’s to stop assuming that loving them means saying yes to every financial opportunity that comes along. When something doesn’t fit financially right now, replace “no” with “not yet,” which can also help shape a healthier relationship with money over the long run.
Triaging priorities isn’t choosing yourself over your children. It’s recognizing that your financial stability is part of what you’re giving them. Sometimes putting your kids first financially means making sure you don’t always put yourself last.
This article was originally published in The Star. Lesley-Anne Scorgie is a Toronto-based personal finance columnist and a freelance contributing columnist for the Star.